Contents
Overview - A Broader VDP Still Has Firm Eligibility Gates
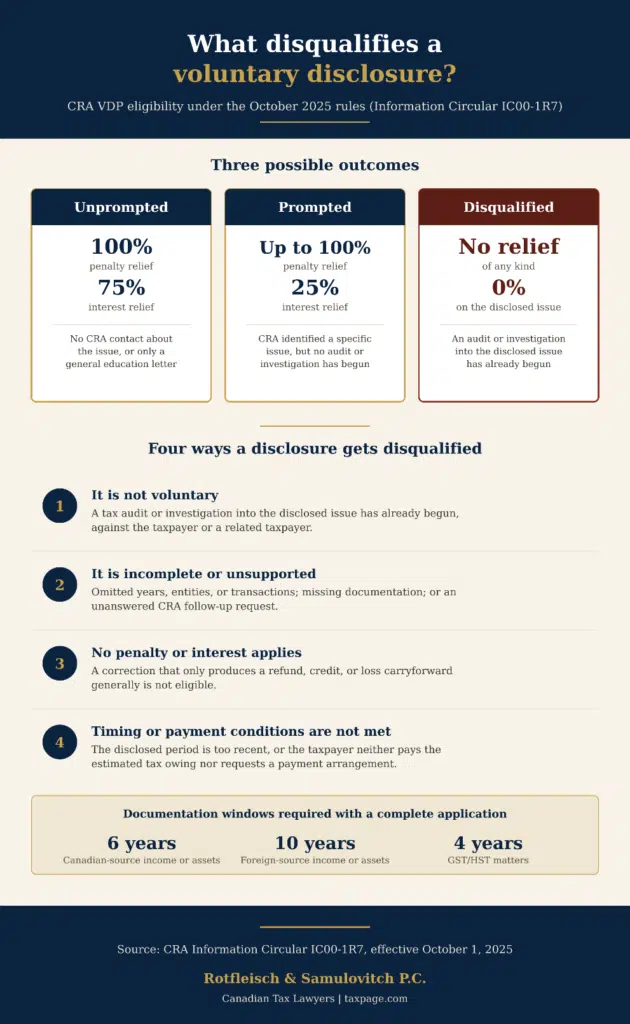
The Disclosure Is Not Voluntary
The Disclosure Is Incomplete, Inaccurate, or Unsupported
No Penalties or Interest Would Otherwise Apply
The Timing and Payment Conditions Are Not Met
Disqualified Versus Prompted: The Critical Distinction
What Happens If the CRA Denies VDP Relief?
Practical Lessons for Preparing a Defensible VDP Application
Key Takeaways for Canadian Taxpayers
Pro Tax Tips: Protect Eligibility Before Contacting the CRA
FAQ: CRA Voluntary Disclosures and VDP Eligibility
Overview - A Broader VDP Still Has Firm Eligibility Gates
If the CRA has already contacted you about unreported income or an unfiled return, don't assume the door is closed. What disqualifies a voluntary disclosure depends on more than whether the Canada Revenue Agency has contacted the taxpayer. Since October 1, 2025, the CRA’s Voluntary Disclosures Program (VDP) has expressly allowed some “prompted” applications. A taxpayer who receives a targeted compliance letter may therefore remain eligible for partial relief if no tax audit or investigation concerning the disclosed issue has begun. This is a significant expansion from the earlier framework, but it is not an automatic tax amnesty.
A VDP application can still fail where:
- it is not voluntary,
- is incomplete,
- concerns no applicable penalties or interest,
- addresses an obligation that is not sufficiently past due, or
- is submitted without payment or a request for a payment arrangement.
- Refund-only adjustments, existing tax assessments, elections, certain insolvency matters, and advance-pricing or competent-authority issues may also be ineligible.
If relief is granted, the taxpayer must still pay the underlying tax. The potential benefits are relief from penalties, partial relief from interest, and protection from referral for criminal prosecution for the disclosed information. Eligibility is decided case by case, and the CRA may verify or tax audit the information even after accepting the application.
Because the timing, completeness, and tax characterization of a disclosure can determine whether relief is available, taxpayers should consult an experienced tax litigation lawyer for CRA disputes before contacting the CRA or filing a VDP application.
“A voluntary disclosure is not simply a confession to the CRA. It is a carefully documented request for discretionary relief. Timing opens the door, but completeness, accurate tax characterization, and a credible payment plan are what keep the application inside the program and ready for judicial review if denied.” David J. Rotfleisch, Certified Specialist in Taxation Law and experienced Canadian Tax Lawyer.
The Disclosure Is Not Voluntary
For income-tax matters, the CRA administers the VDP under Information Circular IC00-1R7, while GST/HST and other covered indirect-tax matters are governed by GST/HST Memorandum 16-5-1; both policies apply to applications received on or after October 1, 2025. The program allows designated CRA officials to exercise statutory discretion to waive or cancel penalties and interest, but relief remains discretionary and subject to the applicable statutory limitation periods.
Generally, an application is not voluntary if a tax audit or investigation has been initiated against the taxpayer, or a related taxpayer, in respect of the information being disclosed. This is not limited to a CRA tax audit. A law-enforcement agency, securities commission, or other federally or provincially regulated authority may also have opened an audit or investigation into the disclosed conduct, and that too can disqualify the application.
The connection between the enforcement activity and the disclosure is essential. An unrelated CRA tax audit or investigation by another authority does not automatically disqualify every possible VDP application by the same taxpayer. The practical question is whether the existing tax audit or investigation concerns the information now being disclosed. A tax audit of corporate expenses, for example, may not necessarily disqualify a separate disclosure of an individual shareholder’s unrelated foreign pension. Conversely, a tax audit of a corporation may affect a shareholder’s application where the corporate review concerns the same transactions or benefits.
In 4053893 Canada Inc v Canada (National Revenue), 2021 FC 218, the CRA had contacted the corporation’s sole shareholder about longstanding non-filing and learned that the corporation remained active with outstanding returns. The Federal Court upheld the CRA’s denial of VDP relief as reasonable because the enforcement activity against the shareholder was sufficiently connected to the corporation and likely to uncover the disclosed information. Although decided under an earlier VDP policy, the case shows that related-party CRA activity should be assessed based on what it actually revealed and how closely it connects to the proposed disclosure.
Taxpayers should reconstruct the chronology before filing: every CRA letter, telephone call, questionnaire, requirement, deadline, portal message, third-party inquiry, and contact with a related entity. Labels are not conclusive. A letter described as a “review” may show that a tax audit has already started, while a general education letter may leave the application unprompted.
The CRA offered further clarification on this line in a June 18, 2026 national webcast with the Society of Trust and Estate Practitioners (STEP) Canada. An audit is a formal review carried out by a CRA auditor, while an investigation covers other active compliance work on a specific issue concerning a specific taxpayer; general or informational CRA contact does not, on its own, cross into either category. The CRA also confirmed that voluntariness is assessed issue by issue rather than across a taxpayer's entire file, so an audit into unreported employment income, for example, does not automatically disqualify a separate disclosure about an unrelated unfiled Form T1135. The CRA further indicated that a general compliance notice sent to cryptocurrency holders reminding them of their reporting obligations would not, on its own, make a resulting disclosure prompted.
The revised policy also makes an important distinction between information and enforcement. If the CRA has received third-party information identifying a taxpayer’s potential non-compliance, the application will generally be prompted. It is not automatically disqualified unless a tax audit or investigation has been initiated. That distinction can preserve VDP access, although at the lower partial-relief level.
“Under the current VDP, CRA contact and a CRA tax audit are no longer synonyms. A specific letter can make an application prompted, but the application becomes ineligible only when the relevant tax audit or investigation has begun. The chronology and the subject-matter connection must be analyzed in detail, not assumed.” David J. Rotfleisch.
The Disclosure Is Incomplete, Inaccurate, or Unsupported
The taxpayer must disclose all known errors and omissions in the relevant tax obligations, including related arm’s-length and non-arm’s-length transactions or circumstances. Selectively correcting favourable years, omitting related entities, minimizing the amounts, or leaving out a transaction that changes the tax characterization can cause the application to be denied and full penalties applied and possibly criminal prosecution commenced. When taxpayers wish to omit information, we advise them of these requirements and risks and refuse to accept the retainer if they insist on an omission. “An incomplete voluntary disclosure is dangerous and worse than no voluntary disclosure at all.” David J. Rotfleisch.
Current CRA guidance also defines the initial documentation windows. For Canadian-source income or assets, supporting returns, forms, schedules, statements, and other documents for the most recent 6 years must generally accompany an income-tax application. Foreign-source income or assets require the most recent 10 years. GST/HST matters generally require the most recent 4 years. A year or reporting period within those windows need not be included if it contains no error or omission, but the CRA may request records outside the standard window.
Where records no longer exist, the taxpayer should make all reasonable reconstruction efforts and provide defensible estimates supported by available financial records and a transparent methodology. If a tax professional, promoter, or another individual assisted with the subject matter, the current Form RC199 also requires that person’s name.
The CRA may deny relief when the initial package lacks enough information, when the taxpayer fails to respond comprehensively and promptly to a request, or when the CRA discovers other non-compliance that was not included. If a deadline cannot be met, an extension should be requested before it expires, with an explanation of what remains outstanding and when it will be delivered.
The Federal Court’s decision in Créations Guimel Inc v Canada (National Revenue), 2025 FC 814 illustrates the risk. The CRA denied an application after the corporation did not provide a requested T2 return despite extensions. The Court found the refusal reasonable and held that the CRA did not owe a final warning before deciding an incomplete application. Although the application was governed by earlier policy, the current circular preserves the same practical warning: the applicant must meet deadlines or seek more time.
No Penalties or Interest Would Otherwise Apply
The VDP is designed to provide relief from consequences that would otherwise arise from an error or omission. An application must therefore involve applicable penalties, interest, or both. A correction that only creates a refund, increases a tax credit, produces a loss carryforward, or yields another benefit, without tax, penalties, or interest otherwise owing, is generally not eligible.
This rule should not be reduced to “tax must be owing.” Some information-return failures can attract penalties, notably but not exclusively the T1135, even where the underlying income was reported, or no additional tax is payable. In that situation, the potential penalty may satisfy the condition. The analysis should identify the exact provision that could impose the penalty or interest and calculate the realistic exposure.
The VDP is also generally unavailable where the taxpayer is merely asking the CRA to cancel penalties or interest already assessed. That request belongs under the taxpayer-relief process rather than the VDP. The distinction matters because the filing route, evidence, remedies, and limitation analysis differ.
The Timing and Payment Conditions Are Not Met
Two additional VDP eligibility conditions concern the age of the tax obligation and how the taxpayer addresses any resulting liability. An application may be denied if the disclosed obligation is not sufficiently past due or if the taxpayer neither pays the estimated tax owing nor requests a payment arrangement.
For income-tax disclosures, the application must include information relating to a taxation year that is at least one year past the filing due date. For GST/HST and other indirect-tax disclosures, it must include information relating to at least one reporting period that is past the filing due date. Taxpayers should identify the applicable reporting frequency and due date rather than treating “one year” as a universal rule. A disclosure dealing only with a recently due return, reporting period, or correction will not satisfy this timing condition.
The timing condition should be reviewed separately from completeness. An application may include older eligible years while the taxpayer must also correct more recent periods to present a complete and current compliance position. A taxpayer should not simply omit a too-recent period if it contains the same continuing error, because selective disclosure may create a separate completeness problem.
Once the timing condition is satisfied, the taxpayer must also address payment. If estimated tax is owing, the taxpayer must submit payment or request a payment arrangement with the VDP application. An immediate inability to pay the full balance is not necessarily disqualifying, but failing to address the liability may be. The application should provide a reasonable estimate of the tax owing, disclose the taxpayer’s financial position where relevant, and propose a realistic payment schedule.
Requesting a payment arrangement does not guarantee approval because CRA collections officials consider that request separately. Interest also generally continues to accrue on unpaid tax. The payment proposal should therefore be prepared with the same care as the substantive disclosure, especially where the application covers several years, payroll remittances, or GST/HST trust amounts.
“A VDP application does not forgive the tax debt. Where liquidity is limited, the correct response is a transparent payment-arrangement request supported by financial evidence, not silence, an unrealistically low estimate, or a promise that cannot be performed.” David J. Rotfleisch.
Disqualified Versus Prompted: The Critical Distinction
The post-October 2025 VDP effectively creates three practical lanes.
An unprompted application is made without verbal or written communication about an identified compliance issue. An application can remain unprompted after a general education letter or notice that provides broad filing guidance without identifying a specific error on the taxpayer’s account. If accepted, it normally receives 100% penalty relief and 75% interest relief.
A prompted application follows communication identifying a specific error or omission, imposing a deadline to correct it, or otherwise expecting compliance. It can also arise when the CRA has already received third-party information about a specific taxpayer’s potential non-compliance. If no related tax audit or investigation has begun, the application may still qualify, but it normally receives only 25% interest relief and up to 100% penalty relief.
A disqualified application fails a core condition. The clearest example is a tax audit or investigation already initiated against the taxpayer or a related taxpayer concerning the disclosed information. In that situation, the application is not voluntary and receives no VDP relief.
This distinction makes the period after a targeted CRA letter strategically important. The taxpayer may already have lost the higher unprompted interest relief, but may still have a narrow opportunity to seek partial relief before the matter progresses to a tax audit or investigation. Delay can convert a prompted but eligible file into an ineligible one.
Form RC199 should be used to establish the application. Once the CRA acknowledges it, the CRA provides an effective date of disclosure, and any relief granted applies up to that date. Taxpayers should not rely on informal communications, an anonymous pre-disclosure discussion, or unfinished internal work as if these steps had secured eligibility. A pre-disclosure discussion is informal, anonymous, and non-binding.
What Happens If the CRA Denies VDP Relief?
A taxpayer who disagrees with a VDP denial can request a second administrative review, identifying the factual, legal, or procedural errors in the first decision and providing any further supporting evidence. Current CRA guidance generally recommends seeking this review before applying to the Federal Court.
If the denial remains in place, the taxpayer may seek judicial review under section 18.1 of the Federal Courts Act, normally within 30 days after the decision is communicated. Judicial review is not a new hearing on the taxpayer’s tax liability. Under Canada (Minister of Citizenship and Immigration) v Vavilov, 2019 SCC 65, a reasonable CRA decision must follow an internally coherent and rational analysis, demonstrate justification, transparency, and intelligibility, and be justified in light of the relevant facts and law. The Court does not decide for itself whether VDP relief should have been granted; it determines whether the CRA’s reasoning or conclusion contains a sufficiently serious flaw. Procedural fairness is considered separately. Even a successful application will usually result in the decision being set aside and returned for reconsideration, rather than automatic VDP acceptance.
The VDP dispute is separate from any challenge to the underlying tax assessment or tax reassessment. The VDP decision itself has no statutory objection route, while disputes about the correctness of an underlying tax assessment generally proceed through a notice of objection and, if necessary, the Tax Court of Canada. Moreover, a pending VDP process does not suspend the CRA's tax assessment powers, so taxpayers should preserve all objection and Tax Court deadlines. Taxpayer-relief provisions or a remission review may also be available in appropriate cases, but they apply different tests and do not replicate VDP protection.
Practical Lessons for Preparing a Defensible VDP Application
The first task is a privileged eligibility review with an experienced Canadian tax lawyer. The taxpayer should identify every CRA and third-party contact, determine whether a related person or entity is under tax audit, and compare that activity with the proposed disclosure. Communications with an accountant are not automatically protected by solicitor-client privilege; where appropriate, accounting assistance can be retained within the legal engagement.
The application should be a reconciled package rather than a narrative alone. A year-by-year and entity-by-entity scope chart can identify corrected reporting, additional tax, potential penalties, supporting records, and remaining gaps. Form RC199, the amended returns, schedules, and payment calculation must agree.
The CRA may tax audit or verify the disclosure whether or not relief is granted. Additional tax assessments may result, and fraud or a misrepresentation attributable to neglect, carelessness, or wilful default can permit a tax reassessment beyond the normal period. The VDP determines relief; it does not finally adjudicate every underlying tax issue.
If relief is denied, the taxpayer may request a second administrative review and make further submissions. There is no statutory right to object to the discretionary VDP decision, and subsection 165(1.2) restricts an objection to the related tax assessment of penalties and interest under subsection 220(3.1). A taxpayer can generally seek judicial review in the Federal Court under section 18.1 of the Federal Courts Act, normally within 30 days after the decision was communicated. The correctness of the underlying tax assessment follows the separate objection and Tax Court route.
The Federal Court of Appeal’s decision in Prince v Canada (National Revenue), 2020 FCA 32 reinforces that a pending VDP process does not suspend the CRA’s tax-assessment powers. Tax assessments remain valid and binding unless varied or vacated through the statutory tax-dispute process. A taxpayer should therefore preserve objection deadlines even while pursuing VDP reconsideration or judicial review.
Privilege Protects a Tax Lawyer's File, Not an Accountant's
Who assembles a voluntary disclosure file matters as much as what goes into it. Communications between a taxpayer and a tax lawyer are protected by solicitor-client privilege, meaning the CRA generally cannot compel their production or seize them, even under audit or search warrant powers. That protection does not extend to an accountant. Working papers, meeting notes, draft reconstructions, and tax planning memos prepared by an accountant are not privileged, and the CRA can and will seize them where it has grounds to do so.
This is not a theoretical risk. The CRA has executed search warrants against accounting firms in the course of tax evasion investigations, seizing client files that included notes of meetings and internal planning memos, and using that material in the resulting prosecution. A voluntary disclosure that is later found to be involuntary, incomplete, or otherwise ineligible can leave the taxpayer facing exactly the kind of scrutiny an accountant's unprotected file is most exposed to.
Privilege can be extended to an accountant's work, but only if the accountant is retained as the tax lawyer's agent for the purpose of giving legal advice, under a written agreement entered into before the work begins. Retaining an accountant directly, or bringing one in only after a CRA letter arrives, will not convert existing working papers into privileged material after the fact. For a disclosure built on years of reconstructed records, this is a structural decision to make at the outset, not a fix to apply once the file is under scrutiny.
Key Takeaways for Canadian Taxpayers
The October 2025 reforms broadened the VDP without removing its eligibility gates. A disclosure may fail when a related tax audit or investigation has started, the application omits known non-compliance or evidence, no penalty or interest exposure exists, the obligation is too recent, or payment is not addressed.
The most important new distinction is between prompted and disqualified. A specific CRA communication or third-party data may reduce the available interest relief without ending eligibility. A tax audit or investigation into the disclosed issue can end eligibility altogether. The timing and subject matter of every contact therefore require careful analysis.
A defensible application combines a complete chronology, legally correct tax characterization, reconciled calculations, supporting records, and a workable payment plan. If the CRA refuses relief, an experienced tax litigation lawyer for CRA disputes can assess a second administrative review, Federal Court judicial review, and the separate objection rights relating to any underlying tax assessment or tax reassessment.
Pro Tax Tips: Protect Eligibility Before Contacting the CRA
Do not contact the CRA first and investigate later. Before any identifiable communication, determine what was not reported, who is affected, whether a related party is under a CRA tax audit, and whether penalty or prosecution exposure exists. An anonymous pre-disclosure discussion is informal and non-binding; legal analysis should precede it.
Speed matters, but a thin filing can be dangerous. Seek the earliest defensible effective date without unsupported assertions or omitted issues. Where records are unavailable, explain the reconstruction method and provide reasonable estimates. If a CRA deadline cannot be met, request an extension before it expires.
Treat tax characterization as part of disclosure. A schedule should not merely list deposits, loans, cryptocurrency trades, shareholder benefits, foreign entities, or property sales. It should explain how each item changes the tax result. The Federal Court of Appeal's decision in Grewal v Canada (Attorney General), 2022 FCA 114, shows that mentioning an amount without disclosing its taxable consequence may leave the taxpayer exposed to penalties, even where the disclosure itself was accepted under the VDP.
Do not abandon the VDP merely because a letter makes the application prompted. Partial relief can still eliminate substantial penalties, reduce interest by 25%, and protect against referral for criminal prosecution. The key is to confirm that the matter has not crossed into a tax audit or investigation and then act promptly with a complete and credible application.
A VDP application or administrative review does not suspend the ordinary deadlines for disputing a tax reassessment. If the CRA issues a tax reassessment, review it immediately and, where appropriate, file a protective Notice of Objection. A separate taxpayer-relief request may address qualifying penalties and interest, but it does not cancel the underlying tax. If the CRA denies discretionary relief, Federal Court judicial review generally examines the reasonableness and procedural fairness of the CRA decision, while the underlying tax assessment or tax reassessment remains subject to the objection and Tax Court process.
“The most expensive VDP mistake is often misclassification. Some taxpayers assume that any CRA letter makes them ineligible and surrender valuable partial relief; others assume that a letter is harmless when a tax audit has already begun. The file chronology should decide the strategy.” David J. Rotfleisch.
FAQ: CRA Voluntary Disclosures and VDP Eligibility
What are the main conditions for a valid voluntary disclosure?
The application must be voluntary, involve a taxation year at least one year past the filing due date or an indirect-tax period at least one reporting period overdue, and concern applicable penalties or interest. It must also include all relevant information and supporting documents, plus payment or a request for a payment arrangement where tax is owing.
Does any CRA contact disqualify a voluntary disclosure?
No. A general education letter may leave an application unprompted. A communication identifying a specific compliance issue generally makes it prompted and reduces interest relief. The application becomes ineligible for lack of voluntariness when a related tax audit or investigation has begun concerning the information being disclosed.
Can I apply after receiving a CRA letter?
Possibly, and receiving a letter is not itself what disqualifies the application. What disqualifies it is a tax audit or investigation into the disclosed issue, not CRA contact in general. A letter identifying a specific error or setting a compliance deadline will generally make the application prompted rather than disqualified, provided no audit or investigation on that issue has started. Because that line can be crossed quickly, and because an audit is a formal review by an auditor while an investigation is any other active compliance work on the specific issue, the letter, account history, related-party activity, and subject matter should be reviewed immediately and the chronology documented before filing.
What is the difference between prompted and unprompted relief?
An accepted unprompted application normally receives 100% penalty relief and 75% interest relief. An accepted prompted application normally receives up to 100% penalty relief and 25% interest relief. Both receive protection from referral for criminal prosecution for the disclosed information and protection from gross-negligence penalties on that information.
Can an unrelated CRA tax audit disqualify my application?
Not necessarily. The current policy asks whether the tax audit or investigation concerns the information being disclosed, including activity involving a related taxpayer, not merely whether an audit exists somewhere in the corporate or family group. In 4053893 Canada Inc v Canada (National Revenue), 2021 FC 218, a corporate audit was found close enough to a shareholder's disclosure to disqualify it, because the audit was likely to uncover the same information. The analysis is fact-specific and outcome-determinative, so the applicant should document why the existing review is unrelated to the disclosed issue rather than relying only on the CRA's label for it.
What makes a voluntary disclosure incomplete?
Common problems include omitted years, accounts, entities, transactions, or tax consequences; inconsistent amended returns; unsupported estimates; missing records; and failure to answer CRA requests. The applicant must disclose all known errors and omissions and provide the prescribed six-year, ten-year, or four-year document package, subject to further CRA requests.
Can I estimate amounts when records are missing?
Yes, where records genuinely do not exist, the CRA expects all reasonable reconstruction efforts and defensible estimates. The application should identify missing records, explain searches undertaken, state assumptions, show the calculation method, and include corroborating evidence. Unsupported round numbers or unexplained estimates can undermine completeness and credibility.
Can the VDP be used only to claim a refund or loss?
Generally no. An adjustment producing only a refund, credit, loss carryforward, or other benefit without applicable tax, penalties, or interest is ordinarily outside the VDP. A failure involving no additional tax may still qualify if a legally applicable information-return or other penalty would otherwise arise.
Must I pay all tax when I submit the application?
The taxpayer must pay the estimated tax owing or request a payment arrangement. Full immediate payment is not always required, but the CRA is not obliged to accept the proposed arrangement. The request should be realistic and supported by financial information, and interest generally continues on unpaid tax.
Can the CRA tax audit an accepted voluntary disclosure?
Yes. Acceptance determines eligibility for relief; it does not guarantee the accuracy or finality of the taxpayer’s tax treatment. The CRA expressly reserves the right to tax audit or verify the information and may issue additional tax assessments. Undisclosed amounts can still attract tax, interest, and penalties.
What can I do if the CRA denies my VDP application?
You may request a second administrative review and provide further representations. If the decision remains unreasonable or procedurally unfair, judicial review may be available in the Federal Court under section 18.1 of the Federal Courts Act, normally within 30 days. The court applies the Vavilov reasonableness standard rather than deciding for itself whether relief should have been granted, and a successful application usually sends the decision back for reconsideration rather than securing automatic acceptance. As Prince v Canada (National Revenue), 2020 FCA 32, confirms, a pending VDP dispute does not pause the CRA's power to reassess, so the separate objection and Tax Court deadlines on the underlying tax assessment must still be preserved.
Can I make a second voluntary disclosure?
Possibly. Taxpayers must remain compliant after being granted VDP relief. The CRA may consider a subsequent application where the circumstances are beyond the taxpayer’s control or the new disclosure relates to a different matter from the previous application. A subsequent application remains discretionary and must otherwise satisfy the VDP eligibility requirements.
DISCLAIMER: This article provides broad information. It is only accurate as of the posting date. It has not been updated and may be out-of-date. It does not give legal advice and should not be relied on as tax advice. Every tax scenario is unique to its circumstances and will differ from the instances described in the article. If you have specific legal questions, you should seek the advice of a Canadian tax lawyer.